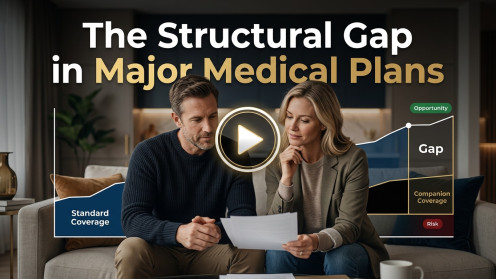
Standard health insurance pays medical bills, but not lost income or diagnosis-related costs. Companion coverage can help with living expenses or treatments outside plan networks.
These policies usually pay cash after specific diagnoses, yet eligibility depends on each policy's covered-condition list, making careful comparison essential before relying on protection.
Income-focused options may start after a waiting period, sometimes 90 days, and can cover partial earning loss, unlike life insurance or narrower disability definitions.
Riders attached to life policies may follow main-policy underwriting, while standalone plans often need separate medical review, changing eligibility, purchase routes, and premium costs.
Digital health record access may speed claims, but data-sharing terms are often hard to spot, and the balance between faster service and privacy remains unresolved.
The Structural Gap in Major Medical Plans | Y Life Financial | Protecting your family, respecting your budget.
Leave a Reply